 uk


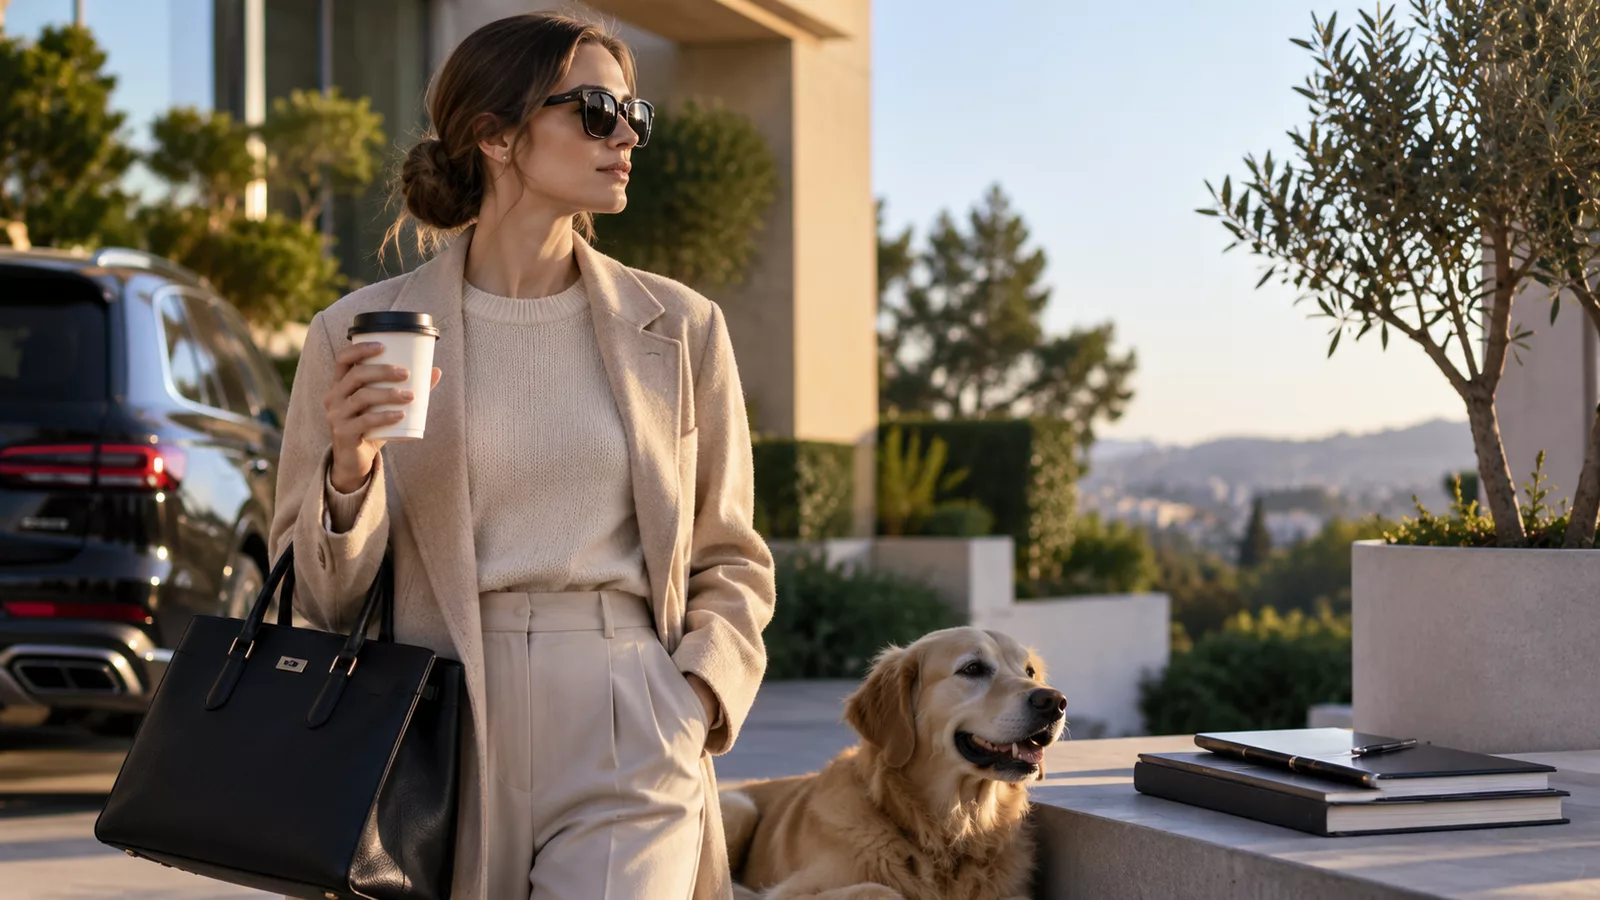
Stealth wealth describes a lifestyle in which someone has significant financial resources but deliberately avoids displaying them through obvious status symbols. A person practicing stealth wealth might have a large investment portfolio while driving an ordinary car, living in a comfortable but relatively modest home and wearing clothes that reveal little about their net worth.
The idea is not simply “rich people who look poor.” Someone can live modestly because they have limited money. Stealth wealth specifically refers to a gap between financial capacity and visible consumption. The person could afford substantially more but chooses not to make wealth highly visible.
That choice can provide greater privacy, reduce pressure to maintain an expensive image and leave more money available for investing or other priorities.
But stealth wealth also has limits. Hiding every purchase, relationship or financial success can turn a sensible preference for privacy into secrecy.
The useful version is simple: own your money without needing your money to introduce you.
What Is Stealth Wealth?
Stealth wealth is the deliberate practice of keeping your financial success relatively private and avoiding unnecessary displays of wealth. It can appear in everyday decisions.
Someone may earn $300,000 a year but continue driving a paid-off Toyota. Another person may have accumulated a seven-figure investment portfolio without regularly discussing investments with friends or coworkers.
The key characteristic is not the brand of car or size of the house. It is the intentional decision not to increase visible consumption simply because financial capacity increased. Stealth wealth can involve:
- Keeping income private.
- Avoiding conspicuous luxury purchases.
- Living below financial capacity.
- Investing income increases instead of spending all of them.
- Limiting financial information shared online.
- Choosing practical purchases despite being able to afford premium alternatives.
- Avoiding lifestyle competition.
- Keeping investment balances and net worth private.
- Spending selectively on things that genuinely matter.
- Separating personal identity from financial status.
None of these behaviors requires being extremely wealthy.
The same principles can be used while someone is still building wealth.
What Does Stealth Wealth Look Like in Real Life?
Imagine two households earning the same $200,000 annual income.
Household A increases spending whenever income rises. It finances expensive vehicles, upgrades to a larger home, buys recognizable luxury products and regularly posts expensive purchases and vacations online.
Household B keeps a comfortable home, replaces vehicles when necessary, spends heavily on a few priorities and directs a larger share of income toward retirement accounts, investments and other financial goals.
Their incomes are identical.
Their visible lifestyles and balance sheets can eventually look completely different.
That illustrates the central idea behind stealth wealth:
Income determines what you can spend. Wealth is influenced by what you keep and own.
A high-consumption household can earn substantially more than a quiet millionaire while having a lower net worth.
Stealth Wealth vs Being Frugal
Stealth wealth and frugality overlap, but they are not identical.
Frugality focuses on using money efficiently and avoiding spending that provides insufficient value.
Stealth wealth focuses more specifically on keeping financial capacity and status relatively invisible.
| Stealth wealth | Frugal living |
|---|---|
| Can involve substantial existing wealth | Can be practiced at any income |
| Emphasizes privacy | Emphasizes spending efficiency |
| Avoids visible status consumption | Avoids unnecessary spending |
| May still include expensive private purchases | Often focuses on getting better value |
| Wealth may greatly exceed visible lifestyle | Lifestyle may simply reflect available income |
| Often connected to financial independence | Often connected to budgeting and saving |
A stealth-wealth household can spend a lot.
It might pay for premium healthcare, private travel, education, hobbies or a high-quality home while avoiding purchases designed primarily to communicate status.
Stealth wealth is selective spending, not necessarily minimal spending.
Stealth Wealth vs Quiet Luxury
Stealth wealth and quiet luxury are frequently confused because both reject highly visible displays of status.
They are still different concepts.
Quiet luxury is primarily an aesthetic and consumption trend. It emphasizes high-quality, often expensive products with subtle branding rather than large logos.
Stealth wealth is a financial behavior.
A $4,000 coat without a visible logo may qualify as quiet luxury, but it is still a $4,000 coat.
Someone practicing stealth wealth might simply buy a durable $200 coat and invest the remaining money.
| Stealth wealth | Quiet luxury |
|---|---|
| Financial/lifestyle strategy | Fashion and consumption aesthetic |
| Wealth is kept relatively private | Expensive products may still signal status subtly |
| Spending may be intentionally restrained | Spending can be very high |
| Focuses on financial resources and privacy | Focuses on understated quality |
| Does not require luxury products | Usually associated with premium products |
You can practice both, either or neither.
The important distinction is that looking understated does not automatically mean someone is practicing stealth wealth.
Why Do Wealthy People Practice Stealth Wealth?
There is no single motivation.
For some people, understated living developed long before they accumulated substantial assets. Their income changed, but their preferences did not.
Others make the decision deliberately after experiencing social pressure connected with money.
Common motivations include:
- Privacy. Fewer people know how much money they may have.
- Security. Public displays can reveal financial information unnecessarily.
- Freedom from lifestyle inflation. Higher income does not automatically create higher fixed expenses.
- Less social pressure. There is less need to maintain an expensive public image.
- More investment capital. Money not consumed remains available for other purposes.
- Simpler relationships. Wealth is less likely to become the first thing others notice.
- Financial flexibility. Lower lifestyle costs can make career changes easier.
- Reduced comparison. Purchasing decisions are less influenced by what peers own.
- Personal values. Some people simply do not enjoy status consumption.
- Long-term independence. Financial security may matter more than appearing financially successful.
These benefits do not require extreme secrecy.
You can keep net worth private while still discussing money openly with a spouse, financial professional or other person who legitimately needs the information.
10 Signs Someone May Be Practicing Stealth Wealth
You cannot reliably determine another person’s net worth from appearance alone.
That is almost the point.
Still, stealth wealth tends to produce several recognizable financial behaviors.
1. Their lifestyle changes slowly when income increases
A raise does not immediately become a more expensive apartment, vehicle, wardrobe and vacation budget.
Some of the additional income goes toward savings, investments or other long-term priorities.
This creates a growing gap between what the person could spend and what they actually spend.
2. They keep cars longer
Vehicles are one of the easiest ways to make income visible.
Someone practicing stealth wealth may choose a reliable vehicle, maintain it carefully and continue driving it long after they could afford something more expensive.
That does not mean always buying the cheapest car.
It means the purchase is based on transportation needs rather than status expectations.
3. Their home is comfortable but not necessarily impressive
Housing can consume an enormous share of income.
A household may qualify for a much larger mortgage but intentionally choose a home that leaves substantial room in the monthly budget.
Lower housing costs can make it easier to invest, travel, change careers or withstand an income interruption.
4. They rarely discuss exact income or net worth
Privacy is central to stealth wealth.
Someone may discuss investing, business or personal finance without revealing exact account balances.
They also avoid using income as a social ranking system.
5. Their expensive purchases are selective
Stealth wealth does not mean refusing every luxury.
Someone may spend $15,000 on a hobby, take an expensive trip or purchase high-quality equipment while driving a relatively ordinary vehicle.
The difference is that spending follows personal priorities rather than a requirement to look wealthy in every category.
6. They avoid obvious lifestyle competition
A neighbor buys a new SUV.
A colleague upgrades to a larger house.
A friend posts a luxury vacation.
None of these events automatically becomes a reason to spend.
The ability to watch other people upgrade without feeling compelled to follow is a powerful financial advantage.
7. They automate wealth building
Quiet wealth accumulation is often boring.
Money moves automatically into retirement accounts, brokerage accounts, savings or other financial goals.
There may be no dramatic monthly decision to “invest.”
It simply happens repeatedly.
8. They pay attention to net worth, not appearances
Income is useful, but it does not show what someone owns after liabilities are considered.
Stealth-wealth thinking tends to emphasize assets, debt and financial independence over visible consumption.
A $150,000 salary with $140,000 of annual spending can create less long-term wealth than a lower income combined with a sustainable savings rate.
9. Their social media reveals little about money
Expensive purchases, account balances and luxury experiences do not need to become public content.
This reduces unnecessary disclosure and also limits the temptation to purchase things partly because they photograph well.
10. They can afford more than you would guess
This is the defining characteristic.
The visible lifestyle understates financial capacity.
A modest car does not mean the owner could not buy a luxury one. An ordinary watch does not reveal the brokerage account behind it.
Stealth wealth makes appearance a poor indicator of net worth.
The Math Behind Stealth Wealth
Stealth wealth becomes easier to understand when lifestyle inflation is translated into numbers.
Suppose two people each receive an additional $1,000 of monthly take-home income.
Person A increases monthly spending by the entire $1,000.
Person B increases lifestyle spending by $300 and invests the remaining $700.
Person B contributes:
$700 × 12 = $8,400 per year
Over 10 years, that represents $84,000 in contributions alone, before considering investment gains or losses.
The visible difference may seem small.
Person A has somewhat nicer purchases every month. Person B has gradually accumulated additional financial assets.
Repeated over several raises and decades, the difference can become substantial.
This is why lifestyle inflation matters so much to stealth wealth.
Lifestyle Inflation Is the Opposite Force
Lifestyle inflation occurs when spending rises as income rises.
Some increase is perfectly reasonable.
Higher income can fund safer housing, better healthcare, childcare, travel, convenience and many other improvements that genuinely improve life.
The problem appears when every raise becomes permanently committed spending.
Consider someone whose take-home income increases by $20,000 per year.
If the entire increase becomes a larger mortgage, vehicle payments and recurring subscriptions, the person’s financial flexibility may barely improve.
If $10,000 goes toward a better lifestyle and $10,000 toward long-term assets, both present and future living standards can improve.
Stealth wealth does not require rejecting lifestyle upgrades.
It requires making them deliberately.
Stealth Wealth Is More About Net Worth Than Salary
A large salary can create the appearance of wealth without producing much actual wealth.
Net worth provides a different perspective.
The simplified calculation is:
Net worth = assets – liabilities
Assets may include:
- Cash.
- Investments.
- Retirement accounts.
- Real estate.
- Business ownership.
- Other valuable assets.
Liabilities may include:
- Mortgages.
- Credit-card balances.
- Student loans.
- Auto loans.
- Personal loans.
- Other debt.
Someone earning $500,000 annually can have a negative net worth.
Someone earning $100,000 can become a millionaire over time.
Income affects the ability to build wealth, but spending, debt, investing and time determine how much is retained.
You Do Not Need to Be a Millionaire to Practice Stealth Wealth
Stealth wealth is often discussed in the context of millionaires, but its core behaviors can begin much earlier.
Suppose you receive your first significant promotion.
You could immediately upgrade several parts of your lifestyle.
Or you could improve the areas that matter most while directing part of the raise toward financial goals.
That decision creates financial margin.
Margin means there is room between income and spending.
The larger that sustainable gap becomes, the easier it can be to build emergency savings, invest, reduce debt and eventually gain more control over work.
You can therefore practice stealth-wealth habits long before you are wealthy.
How Much Should You Save to Build Stealth Wealth?
There is no official stealth-wealth savings percentage.
Your appropriate savings rate depends on income, expenses, debt, retirement goals, family circumstances and starting point.
One useful retirement-planning benchmark from Fidelity assumes saving about 15% of pretax income annually, including employer contributions, beginning at age 25 under its baseline assumptions.
That is a retirement-planning guideline, not a stealth-wealth rule.
Someone pursuing financial independence may choose a substantially higher savings rate, while a person paying expensive debt or managing high childcare costs may initially save less.
The important behavior is preventing spending from automatically absorbing every increase in income.
For example:
| Monthly raise after tax | Added monthly spending | Added monthly saving/investing | Added annual saving/investing |
|---|---|---|---|
| $300 | $150 | $150 | $1,800 |
| $500 | $250 | $250 | $3,000 |
| $1,000 | $400 | $600 | $7,200 |
| $1,500 | $500 | $1,000 | $12,000 |
| $2,000 | $750 | $1,250 | $15,000 |
The table does not prescribe how a raise should be divided.
It demonstrates how even partial control of lifestyle inflation can create substantial additional investment capacity.
Automating Money Makes Stealth Wealth Easier
Stealth wealth works best when good financial decisions do not require constant willpower.
Automatic transfers can move money toward savings or investments soon after income arrives.
That reduces the temptation to interpret the entire account balance as spendable cash.
A simple system might separate:
Bills → emergency savings → investing → planned goals → discretionary spending.
The transfers do not need to be complicated.
Consistency matters more than having dozens of accounts.
The same principle applies to money leaving your account. Reviewing recurring payments can help identify automatic expenses that quietly expanded as income increased.
Automation should make intentional financial behavior easier, not make forgotten spending invisible.
Stealth Wealth and Investing
Investing is often central to stealth wealth because the difference between income and consumption needs somewhere to go.
That does not mean stealth wealth requires speculative investments or complex trading.
In fact, constantly displaying trades, investment wins and account screenshots conflicts with the privacy element of the concept.
A long-term strategy may involve retirement accounts, diversified investments and other assets appropriate to the person’s goals and risk tolerance.
The exact portfolio is individual.
What matters is the shift from asking:
“What can this income buy me today?”
to:
“How much financial freedom can this income build over time?”
That change in perspective is more important than any particular stock, ETF or investment trend.
Stealth Wealth and Retirement Accounts
Retirement accounts can fit naturally into stealth wealth because contributions increase financial assets without creating visible lifestyle consumption.
In the U.S., the employee elective-deferral limit for most 401(k) plans is $24,500 in 2026.
The combined contribution limit for traditional and Roth IRAs is $7,500 for 2026 for people under 50, subject to applicable eligibility and income rules.
These are contribution limits, not recommended amounts for every person.
Someone does not need to maximize every account to practice stealth wealth.
The broader idea is to use increasing financial capacity to strengthen the balance sheet rather than automatically increasing visible consumption.
Stealth Wealth and Your Home
A home is one of the biggest opportunities for lifestyle inflation.
Lenders may approve a mortgage substantially larger than the amount you actually need to spend on housing.
Stealth-wealth thinking asks a different question:
How much house supports the life I want without consuming unnecessary financial flexibility?
A smaller mortgage can potentially leave more money for investing, travel, childcare, entrepreneurship or early retirement.
But buying the cheapest possible home is not automatically smart.
Location, safety, commute, family needs, maintenance and long-term plans matter.
Stealth wealth is not about minimizing every expense.
It is about refusing to maximize an expense simply because you technically can.
Stealth Wealth and Cars
Cars are particularly visible, which makes them closely associated with status.
A stealth-wealth approach might involve buying a reliable vehicle that fits actual transportation needs and keeping it for years.
Again, this does not require buying the cheapest car available.
Safety, reliability, comfort and personal enjoyment have value.
The financial question is whether a more expensive vehicle genuinely improves your life enough to justify the additional purchase price, financing cost, insurance, depreciation and opportunity cost.
A $70,000 car is not automatically irresponsible for someone who can comfortably afford it.
It simply makes more of that person’s wealth visible – and commits more capital to transportation.
Stealth Wealth and Clothing
Clothing provides another useful example because brand visibility and price can be only loosely connected to practical utility.
Someone practicing stealth wealth may buy high-quality clothes without caring whether other people recognize the brand.
Another person may prefer inexpensive basics.
Neither choice defines stealth wealth by itself.
The key question is whether purchases are being made primarily for personal value or to communicate financial status.
Buying quality is compatible with stealth wealth.
Buying recognition is where the distinction becomes clearer.
Stealth Wealth and Social Media
Social media makes wealth more visible than it has ever been.
Homes, vacations, restaurant bills, luxury products and investment results can all be published instantly.
This creates two financial risks.
First, you may disclose more personal financial information than necessary.
Second, repeated exposure to other people’s curated consumption can shift your own perception of what is “normal.”
A luxury vacation seen online tells you almost nothing about the person’s financial position.
It could have been paid in cash from substantial wealth.
It could also have been financed with debt.
Stealth wealth removes much of this comparison by making personal finances less performative.
You do not need an audience for a good financial decision.
Privacy Does Not Mean Hiding Money From Authorities
This distinction is critical.
Stealth wealth means limiting unnecessary public disclosure and conspicuous consumption.
It does not mean concealing income, accounts or assets when disclosure is legally required.
Tax agencies, courts, lenders, business partners or other parties may have legitimate legal reasons to require financial information depending on the circumstances.
Tax obligations do not disappear because someone prefers financial privacy.
The same applies to financial institutions’ reporting and verification requirements.
Stealth wealth is a lifestyle choice, not a method for hiding legally reportable assets.
Privacy Does Not Mean Hiding Money From Your Spouse
Healthy financial privacy and financial secrecy are not the same thing.
A married or financially interdependent couple usually needs enough transparency to make informed joint decisions.
Secret accounts, hidden debts or undisclosed major purchases can create financial and relationship problems.
You can practice stealth wealth as a household while keeping finances private from the outside world.
That might mean the couple knows the complete financial picture while friends, coworkers and social-media followers do not.
The people who legitimately share responsibility for financial decisions should not be kept uninformed merely in the name of stealth wealth.
How Stealth Wealth Can Protect Financial Flexibility
Visible lifestyle upgrades often create invisible recurring obligations.
A larger home can mean higher taxes, insurance, maintenance and utilities.
A more expensive vehicle can increase insurance and financing costs.
Memberships, subscriptions and services can add another layer of fixed monthly spending.
Once enough expenses become permanent, a high salary may no longer feel optional.
Stealth wealth can preserve flexibility because a smaller percentage of income is committed.
That can make it easier to:
- Leave an unhealthy job.
- Take a career break.
- Start a business.
- Work fewer hours.
- Handle unemployment.
- Move.
- Support family.
- Retire earlier.
- Absorb an unexpected expense.
The real luxury may be having fewer financial decisions forced on you.
Does Stealth Wealth Make You Richer?
Not automatically.
Driving an old car does not create wealth if the money saved is simply spent elsewhere.
The financial benefit appears when lower visible consumption translates into a higher savings rate, lower debt or more investment assets.
Suppose you decide against a $700 monthly vehicle payment and instead invest $500 per month while keeping $200 for additional spending.
That creates:
$500 × 12 = $6,000 per year of contributions.
Over 10 years, that equals $60,000 contributed before investment gains or losses.
The wealth effect therefore comes from what happens to the unspent money, not from appearing modest.
Pros and Cons of Stealth Wealth
Keeping wealth understated can provide substantial benefits, but it is not automatically healthy in every form.
| Potential advantages | Potential disadvantages |
|---|---|
| More financial privacy | Can become excessive secrecy |
| Less lifestyle inflation | May lead to unnecessary deprivation |
| More money available for investing | Friends may misunderstand financial choices |
| Less pressure to signal status | Can make generosity feel complicated |
| Greater financial flexibility | Constantly hiding success can become stressful |
| Reduced social comparison | Can create awkwardness in close relationships |
| Less public financial information | May become overly focused on appearing ordinary |
| Spending follows personal priorities | Can discourage spending even when affordable |
The objective should not be pretending you have less money than you do.
A healthier goal is simply refusing to make net worth a public performance.
The Risks of Taking Stealth Wealth Too Far
A financial strategy stops being useful when it makes life worse without creating meaningful benefits.
Stealth wealth can become unhealthy if you:
- Refuse reasonable comforts despite strong finances.
- Feel guilty about every discretionary purchase.
- Hide important financial information from a spouse.
- Avoid necessary healthcare to preserve savings.
- Never celebrate financial progress.
- Refuse to help others solely because it might reveal wealth.
- Become suspicious of every relationship.
- Let money secrecy create isolation.
- Optimize net worth while ignoring quality of life.
Wealth is a resource.
Accumulating it indefinitely without allowing it to support your life can become another form of imbalance.
Stealth Wealth Does Not Mean Never Buying Luxury
There is no rule against luxury.
The distinction is intentionality.
If you love watches and can comfortably afford one, buying an expensive watch does not erase years of sensible financial decisions.
The same applies to cars, travel, restaurants, fashion or hobbies.
A practical framework is to spend generously in a few categories that matter and remain indifferent in categories that do not.
For example:
Love travel? Spend more on travel.
Do not care about cars? Keep the reliable one.
Love cooking? Buy excellent kitchen equipment.
Do not care about fashion? Ignore designer labels.
This approach can produce a high-quality life without requiring every purchase to signal wealth.
How to Practice Stealth Wealth Without Feeling Deprived
Stealth wealth works best when it reflects personal values rather than financial fear.
Start by defining what you genuinely enjoy.
Then separate those priorities from spending driven primarily by comparison.
A practical approach is:
- Choose your high-value spending categories.
- Keep fixed expenses comfortably below your maximum capacity.
- Automate saving and investing.
- Avoid automatic lifestyle upgrades after raises.
- Keep income and net worth relatively private.
- Spend without guilt on priorities already included in your plan.
- Review whether frugality is still improving your life.
The final step is important.
A strategy developed when you had $5,000 may not need to remain identical after you have accumulated $500,000.
Financial habits should evolve as circumstances change.
How to Start Building Stealth Wealth in 2026
You do not need to change your entire lifestyle.
Start with the gap between what you earn and what you spend.
Step 1: Calculate your net worth
List assets and liabilities.
Do not worry about whether the number looks impressive.
You need a starting point.
Step 2: Calculate your savings rate
Determine how much income is actually being retained for future goals.
If income rose significantly but savings did not, lifestyle inflation may be absorbing the difference.
Step 3: Build an emergency reserve
Stealth wealth should create financial resilience, not merely investment balances.
Keep enough accessible cash for unexpected expenses based on your circumstances.
Step 4: Review expensive debt
High-interest debt can work against wealth accumulation even when the outward lifestyle appears modest.
Know what each debt costs.
Step 5: Automate long-term saving
Move money toward retirement or other financial goals automatically where appropriate.
Step 6: Capture part of every raise
Decide how much of a future raise can improve your current lifestyle and how much will strengthen future finances.
Make the decision before the higher income becomes normal.
Step 7: Reduce unnecessary financial disclosure
Stop publishing information that does not need to be public.
That can include exact income, account balances and expensive purchases.
Step 8: Spend intentionally
Do not replace conspicuous consumption with competitive frugality.
Spend on things you value.
Step 9: Review progress annually
Track net worth, debt, savings and investment contributions.
Visible lifestyle is not the metric.
Financial resilience is.
A Simple Stealth Wealth Example
Consider a hypothetical 35-year-old earning $120,000.
After taxes and deductions, assume monthly take-home pay is $7,000 for illustration.
The person could structure that money in many ways.
One example is:
| Category | Monthly amount |
|---|---|
| Housing and utilities | $2,000 |
| Food | $700 |
| Transportation | $500 |
| Insurance/health | $500 |
| Lifestyle and entertainment | $800 |
| Travel/goal fund | $500 |
| Additional saving/investing | $1,500 |
| Other | $500 |
| Total | $7,000 |
This is not a recommended budget.
The important feature is the $1,500 gap intentionally directed toward financial assets rather than automatically becoming additional lifestyle spending.
That represents $18,000 annually before considering any workplace retirement contributions.
Someone seeing the person’s home or car would have no reason to know how much is being accumulated.
That is stealth wealth in practice.
Stealth Wealth and Financial Independence
Stealth wealth and financial independence fit naturally together.
Financial independence generally requires building enough assets to support substantial parts of your future lifestyle.
The amount required depends heavily on how expensive that lifestyle is.
Someone who needs $60,000 annually to support a satisfying life requires a different asset base from someone whose lifestyle requires $200,000.
Controlling lifestyle inflation can therefore affect both sides of the equation:
More money may be available to invest today.
Less money may be required to support the desired lifestyle later.
That combination helps explain why understated consumption can be powerful even without an unusually high income.
How to Keep Digital Money Management Private
Stealth wealth increasingly includes digital privacy. Financial information can appear in emails, account notifications, screenshots, payment histories and devices. Use strong account security and avoid publicly sharing screenshots that reveal balances or transaction details.
Also understand what each financial service is designed to do. For example, the WeaveMoney Perfect Money payment system review looks at funding, transfers, withdrawals and fees – the types of practical details that matter before using any financial platform.
Privacy should not mean keeping money in unsuitable services. Security, regulation, accessibility and purpose still matter more than simply keeping financial activity out of sight.
Common Stealth Wealth Mistakes
The concept sounds simple, but it can easily become distorted.
Avoid these mistakes:
- Pretending to be poor.
- Refusing purchases you can comfortably afford and genuinely value.
- Hiding money from a spouse or partner who should know about it.
- Confusing privacy with illegal concealment.
- Keeping excessive cash simply because investing feels too visible or risky.
- Making frugality part of your social status instead of rejecting status competition.
- Judging people who enjoy luxury purchases.
- Ignoring appropriate insurance.
- Avoiding professional financial or tax help to preserve secrecy.
- Never adjusting your lifestyle after your finances improve.
- Assuming an ordinary appearance proves someone is wealthy.
- Treating stealth wealth as a personality rather than a financial choice.
The goal is not to win a competition for looking the least wealthy.
It is to make money decisions without needing outside validation.
Stealth Wealth Checklist for 2026
Before adopting the lifestyle, ask whether each behavior improves your finances or merely creates another restriction.
| Question | Healthy direction |
|---|---|
| Do I know my net worth? | Track it privately |
| Does spending rise with every raise? | Keep part of income growth |
| Do I have emergency savings? | Build appropriate accessible reserves |
| Am I investing for long-term goals? | Create a consistent strategy |
| Do I buy things mainly to impress people? | Spend according to personal value |
| Do I share financial details publicly? | Limit unnecessary disclosure |
| Am I hiding finances from people who legitimately need to know? | Maintain appropriate transparency |
| Am I refusing things I genuinely value despite being able to afford them? | Avoid unnecessary deprivation |
| Do I understand my recurring expenses? | Review them periodically |
| Does my lifestyle leave financial flexibility? | Avoid unnecessary fixed obligations |
A useful stealth-wealth strategy should make finances less stressful and more flexible, not turn money into something that must constantly be hidden.
Is Stealth Wealth Worth It?
Stealth wealth can be useful when it helps you avoid lifestyle inflation, protect financial privacy and keep more choices available.
Its strongest principle is not “never look rich.”
It is do not spend money simply to make sure other people know you have it.
That distinction leaves room for an enjoyable life.
You can travel, own a beautiful home, buy excellent products and spend heavily on experiences that matter to you.
You simply do not need every part of your lifestyle to operate at the maximum level your income could support.
For people still building wealth, that creates room to save and invest.
For people who are already wealthy, it can create privacy and reduce pressure to maintain a public financial identity.
The balance is important.
Stealth wealth should make money quieter – not make life smaller.
FAQ About Stealth Wealth
Stealth wealth means having more financial resources than your visible lifestyle suggests and intentionally keeping income, assets or net worth relatively private.
A person with a seven-figure investment portfolio who drives a practical car, lives in a comfortable but modest home and rarely discusses money publicly could be practicing stealth wealth.
No. Frugality focuses primarily on spending efficiently. Stealth wealth focuses on keeping financial capacity relatively private and avoiding unnecessary status consumption. The two behaviors can overlap.
No. Quiet luxury generally describes expensive but understated products. Stealth wealth is a broader financial behavior and does not require buying luxury products at all.
Some wealthy people keep finances private to reduce social pressure, protect privacy, avoid lifestyle inflation or separate personal relationships from financial status. Motivations vary by individual.
You generally cannot know with confidence. An ordinary lifestyle reveals very little about income, assets, debt or net worth, which is one reason the concept is called stealth wealth.
Yes. You can avoid unnecessary lifestyle inflation, keep finances private and direct part of income growth toward long-term assets before reaching a high net worth.
Often, but living below your means is only one part of the concept. Stealth wealth also emphasizes privacy and avoiding conspicuous displays of financial capacity.
It can help preserve privacy, reduce lifestyle inflation and increase financial flexibility. Taken too far, however, it can become excessive secrecy or unnecessary deprivation.
Some do. Stealth wealth does not prohibit luxury spending. The difference is that purchases tend to follow personal priorities rather than a need to publicly demonstrate financial status.
No. Stealth wealth refers to personal privacy and lifestyle choices. It does not remove tax, reporting, disclosure or other legal obligations.
Track your net worth, control lifestyle inflation, automate saving or investing where appropriate, limit unnecessary public disclosure and spend selectively on things that genuinely improve your life.
Turning financial privacy into extreme secrecy or deprivation. Stealth wealth should increase financial freedom rather than make you afraid to spend money you can responsibly afford. praying for money
Dmytro Mykhailenko is a financial expert and a prolific author specializing in articles about money and economics. With a deep understanding of financial matters, he provides readers with valuable insights into financial planning, investing, and economic trends. His informative and practical articles help readers navigate complex financial issues and make well-informed decisions.