 uk


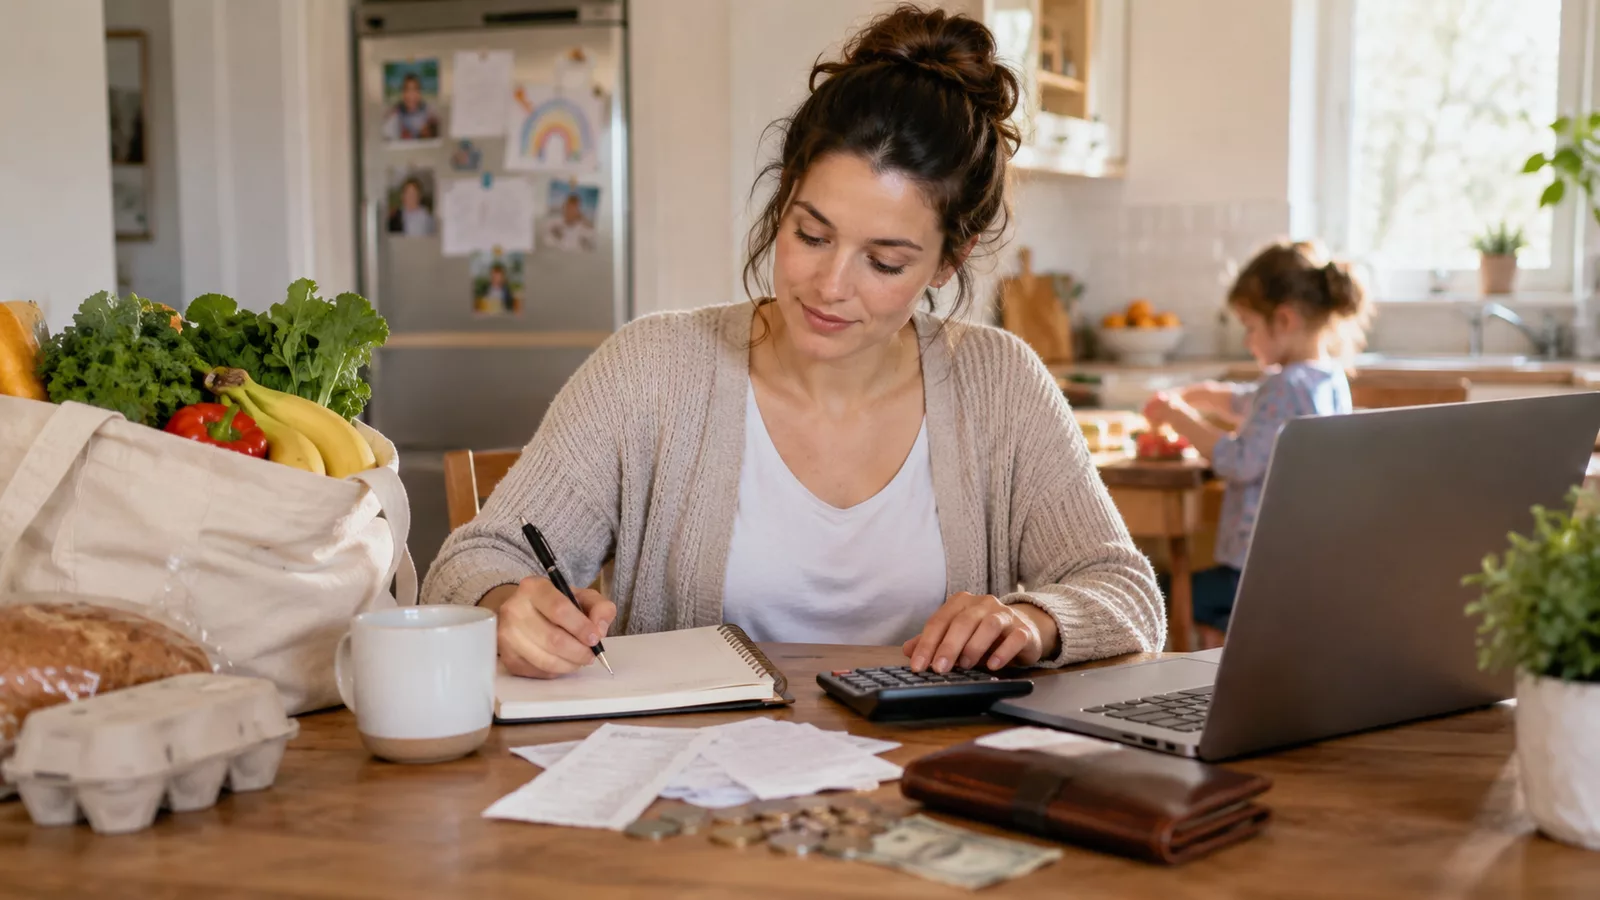
Budgeting for moms can feel very different from creating a simple personal budget. A household may need to cover groceries, housing, childcare, school expenses, transportation, medical costs and dozens of small purchases that seem to appear without warning.
The solution is not to build a perfect spreadsheet that assumes every month will behave exactly the same. A useful family budget needs room for irregular expenses, changing needs and the unexpected costs that come with raising children.
Start with what your household actually earns and spends rather than what an online budgeting formula says you should spend. Then prioritize essential expenses, plan for predictable-but-irregular costs and gradually build savings for genuine emergencies.
This guide walks through the process step by step and includes a family budget template you can adapt to your own numbers.
Budgeting for Moms in 2026 at a Glance
A family budget is simply a plan for deciding where household income needs to go before money disappears into dozens of unrelated expenses.
The basic process looks like this.
| Step | What to do |
|---|---|
| 1 | Calculate reliable household income |
| 2 | Track actual spending |
| 3 | List essential family expenses |
| 4 | Identify irregular child-related costs |
| 5 | Create sinking funds |
| 6 | Set realistic grocery spending |
| 7 | Review childcare costs |
| 8 | Build emergency savings |
| 9 | Make a debt plan |
| 10 | Automate useful payments and savings |
| 11 | Review the budget every month |
You do not need to complete every step perfectly during the first month. The first budget is a starting point that becomes more accurate as you collect real spending data.
1. Start With Your Real Take-Home Income
The first number in a family budget should be the money your household can actually use.
Do not build the budget around gross salary before taxes and payroll deductions. Use take-home income deposited into your accounts, plus other reliable sources of money available for household expenses.
Depending on your circumstances, income can include:
- Salary or wages.
- Self-employment income.
- Freelance income.
- Child support.
- Government benefits.
- Regular bonuses or commissions.
- Rental income.
- Other dependable household income.
If your household receives $6,000 per month before taxes but only $4,700 reaches your accounts, $4,700 is the more useful starting point for the monthly spending plan.
Be cautious with irregular money. An occasional bonus should not automatically be used to justify a permanent monthly expense.
2. Look at What Your Family Actually Spends
One of the biggest budgeting mistakes is creating an imaginary version of your spending.
You may decide that groceries “should” cost $600 a month when your family has consistently spent $850. Writing $600 in a spreadsheet does not automatically reduce the grocery bill by $250.
Instead, review the last two or three months of bank and credit-card transactions.
Group spending into categories such as:
- Housing.
- Utilities.
- Groceries.
- Childcare.
- Transportation.
- Insurance.
- Healthcare.
- Debt payments.
- School and children.
- Subscriptions.
- Eating out.
- Entertainment.
- Clothing.
- Savings.
- Miscellaneous expenses.
The goal during this stage is observation, not judgment.
Once you know where the money actually goes, you can decide which numbers need to change.
3. Separate Needs, Commitments and Wants
Not every household expense has the same priority.
When money becomes tight, separating expenses into groups makes it easier to decide what gets paid first.
| Category | Examples |
|---|---|
| Essential needs | Housing, food, utilities, essential medicine |
| Essential family costs | Childcare needed for work, school necessities |
| Financial commitments | Minimum debt payments, insurance |
| Important goals | Emergency savings, retirement, education savings |
| Flexible spending | Restaurants, entertainment, nonessential shopping |
| Optional recurring costs | Streaming, apps, memberships |
Some categories can move depending on your circumstances. A car can be essential for one family and optional for another. Childcare can be necessary for a working parent but structured differently in another household.
A good budget reflects your family’s reality rather than someone else’s definition of the perfect household.
4. Create a Monthly Family Budget
Once you know income and actual spending, put everything into one monthly plan.
Suppose a household has $5,000 in monthly take-home income.
| Category | Example monthly amount |
|---|---|
| Take-home income | $5,000 |
| Housing | $1,500 |
| Utilities and internet | $350 |
| Groceries | $700 |
| Childcare | $700 |
| Transportation | $400 |
| Insurance | $250 |
| Healthcare | $150 |
| Minimum debt payments | $250 |
| Emergency savings | $200 |
| Sinking funds | $200 |
| Family entertainment | $150 |
| Personal spending | $150 |
| Miscellaneous | $100 |
| Total | $5,000 |
These are illustrative numbers, not spending targets.
Your housing could be substantially higher while childcare is lower, or the reverse. The purpose of the example is to give every dollar a job without pretending every family should use identical percentages.
5. Budget for the Kids’ Expenses You Know Are Coming
A school trip in May is not really an emergency if you knew about it in January.
The same applies to birthdays, school supplies, holiday gifts, children’s clothing and many other expenses that do not happen every month.
This is where many family budgets break down.
List predictable annual and semiannual expenses such as:
- Birthdays.
- Christmas or other holidays.
- School supplies.
- School trips.
- Sports registration.
- Uniforms.
- Children’s clothing.
- Shoes.
- Camps.
- Annual memberships.
- Dental expenses.
- Back-to-school shopping.
Estimate the annual cost and divide it by 12.
If you expect to spend $600 on children’s clothing throughout the year:
$600 ÷ 12 = $50 per month
Putting $50 aside every month turns a large irregular purchase into a manageable part of the normal budget.
6. Use Sinking Funds for Irregular Family Expenses
A sinking fund is money saved gradually for a specific future expense.
It is different from an emergency fund because you already know, at least approximately, what the money will eventually be used for.
A family might create sinking funds for:
| Sinking fund | Monthly contribution | Annual amount |
|---|---|---|
| Children’s clothes | $50 | $600 |
| Birthdays | $40 | $480 |
| Christmas/holidays | $75 | $900 |
| School expenses | $50 | $600 |
| Car maintenance | $75 | $900 |
| Family travel | $100 | $1,200 |
| Home maintenance | $75 | $900 |
You do not need seven separate bank accounts. Some banks allow savings “buckets,” while a spreadsheet can also track how one savings balance is allocated.
The important part is that the money is reserved before the expense arrives.
Sinking funds turn predictable financial surprises into planned expenses.
7. Build a Grocery Budget That Is Actually Possible
Groceries are one of the most visible and frustrating family expenses because prices, appetites and schedules change.
Begin with what your household currently spends rather than picking an arbitrary target.
If the average over the last three months is $900, trying to immediately spend $450 may create a budget that fails within two weeks.
Instead, look for specific changes.
Plan several dinners before shopping. Check what is already in the refrigerator, freezer and pantry. Compare unit prices rather than package prices. Reduce food waste before cutting foods your family actually eats.
Also separate groceries from restaurants and takeout.
If both categories are mixed together, it becomes difficult to understand whether rising food spending comes from supermarket prices or convenience meals.
8. Create a Childcare Budget
Childcare can be one of the largest expenses in a household with young children.
Include the full cost rather than only the regular daycare or babysitter payment.
Depending on your situation, childcare spending may include:
- Daycare.
- Preschool.
- Babysitters.
- Before-school care.
- After-school care.
- Summer programs.
- School-break coverage.
- Late pickup charges.
- Registration fees.
- Meals or supplies.
- Transportation.
Some costs may change when a child starts school, during summer or when work schedules change.
Look at childcare across the entire year rather than assuming the same monthly payment applies forever.
If summer care costs significantly more, start setting money aside before summer arrives.
9. Budget on One Income When Possible – But Only If the Numbers Work
Some two-income households choose to structure core expenses around one income and direct part of the second income toward savings, debt or other goals.
This can create flexibility if one parent temporarily leaves work, takes parental leave or experiences a job loss.
But it is not realistic for every family.
If housing, childcare, food and other essential costs already require both incomes, forcing a one-income budget onto the household can create unnecessary frustration.
Instead, calculate what would happen if one income disappeared.
Which expenses would change immediately? Would childcare decrease? How long could savings cover the gap? Which spending could be paused?
Even if living entirely on one income is impossible, knowing the answer before a job loss occurs improves financial preparedness.
10. Budget With Irregular Income
Budgeting for moms becomes more complicated when income changes every month.
Freelancers, commission-based workers, business owners and hourly workers may not know exactly how much the next paycheck will contain.
In this situation, consider building the essential budget around a conservative income estimate.
Suppose your monthly income during the last six months was:
$3,600, $4,800, $4,200, $5,100, $3,900 and $4,600.
Building fixed expenses around $5,100 would leave very little room during weaker months. A more conservative baseline can reduce that risk.
When a higher-income month arrives, the additional money can go toward:
- Upcoming irregular expenses.
- Emergency savings.
- Debt.
- Annual bills.
- Retirement.
- Other financial goals.
Variable income makes cash reserves particularly valuable because they can smooth the difference between strong and weak months.
11. Start an Emergency Fund – Even If You Can Only Save a Little
An emergency fund is money reserved for genuine unexpected expenses such as urgent repairs, medical bills or loss of income.
Families with children can face frequent financial surprises, so having accessible savings can reduce reliance on credit cards or loans.
You do not need to wait until you can save hundreds of dollars each month.
If $25 per payday is realistic, start with $25. The first objective can simply be building enough to absorb a modest unexpected bill.
Then increase the goal over time.
| Milestone | Purpose |
|---|---|
| $250 | Small unexpected expenses |
| $500 | Larger minor emergencies |
| $1,000 | Basic starter cushion |
| 1 month of essential expenses | Short income disruption |
| Several months of essential expenses | Greater protection against major disruption |
These are examples rather than universal rules. The appropriate emergency fund depends on income stability, household expenses, insurance, number of earners and other circumstances.
The CFPB notes that even a small amount of emergency savings can provide financial security and help households recover from unexpected expenses without immediately turning to debt.
12. Keep Emergency Savings Separate From Sinking Funds
Emergency savings and sinking funds solve different problems.
Your emergency fund is for events you did not reasonably expect. Sinking funds cover expenses you know are coming.
Your child’s birthday is not an emergency. Neither is annual car registration or Christmas.
A sudden essential car repair could be.
Keeping these categories separate prevents predictable expenses from repeatedly emptying the emergency fund.
If all savings sit in one account, track the balances separately so you know how much is genuinely available for emergencies.
13. Make a Debt Plan That Fits the Family Budget
Debt repayment is important, but a plan that leaves no money for groceries or necessary childcare will not survive for long.
Start by recording:
- Creditor.
- Current balance.
- Interest rate.
- Minimum payment.
- Due date.
Always account for required minimum payments in the regular budget.
If extra money is available, you can decide how to prioritize additional repayment. Some people focus on high-interest debt first, while others prefer clearing smaller balances for psychological momentum.
The right strategy is one you can maintain while continuing to meet essential family expenses.
Also consider whether having at least a small emergency cushion before making aggressive extra payments could reduce the chance of immediately borrowing again after an unexpected expense.
14. Review Recurring Payments and Family Subscriptions
Recurring payments can make family life easier, but they can also make spending invisible.
Streaming services, children’s apps, cloud storage, fitness memberships, meal subscriptions and software can continue charging automatically long after the household stops using them.
Review recurring transactions at least several times a year.
Ask:
- Do we still use this?
- Would we buy it again today?
- Has the price increased?
- Are two subscriptions doing the same thing?
- Is an annual plan cheaper for something we genuinely use?
- Can this expense be paused?
Automatic payments are useful for essential bills when sufficient money is available. WeaveMoney’s guide explaining recurring payments covers how automated charges work and why monitoring them remains important.
Saving $10 on one subscription will not transform a family budget. Finding five forgotten recurring charges, however, can create meaningful room over a year.
15. Give Yourself Personal Spending Money
A family budget should not make every personal purchase feel like a financial failure.
If the household can afford it, include a reasonable amount of personal spending for each adult.
That money can cover coffee, hobbies, clothes or other small wants without requiring a debate over every purchase.
The amount matters less than agreeing on the rules.
For couples, equal personal spending allowances can also reduce conflict when incomes differ. Household contributions do not have to determine who is “allowed” to spend more on themselves.
If money is extremely tight, personal spending may temporarily need to shrink. But a sustainable budget should eventually make room for life beyond bills.
16. Budget for Yourself, Not Only the Kids
Parents can become so focused on children’s immediate needs that their own long-term finances disappear from the plan.
Your retirement, healthcare and financial security still matter.
Spending everything on children today can create financial dependence later. Where possible, maintain long-term savings alongside child-related goals.
This can require uncomfortable prioritization.
For example, paying for every optional children’s activity while saving nothing for emergencies or retirement may not be sustainable.
Supporting children financially is important, but a parent’s future financial stability is also part of the family’s financial wellbeing.
17. Saving for Kids vs Saving for Retirement
Parents frequently face a difficult choice between saving for children’s future education and their own retirement.
The two goals are not identical.
Depending on your country, children may have access to scholarships, loans, grants, work or lower-cost education alternatives. Retirement expenses generally cannot be financed in the same way.
This does not mean you should never save for a child’s education. It means retirement should not automatically disappear from the budget simply because parenting creates more immediate goals.
If both cannot be fully funded, determine what contribution is realistic without compromising essential household stability.
Long-term investing also requires understanding risk and time horizon. WeaveMoney’s guide on how to invest in stocks explains some of the fundamentals for beginners considering ownership-based investments for longer-term goals.
18. Create a Budget for Back-to-School Season
Back-to-school spending can feel like an emergency when it arrives all at once.
Instead, estimate the cost several months in advance.
Include:
- School supplies.
- Backpack.
- Clothing.
- Shoes.
- Uniforms.
- Technology.
- Activity fees.
- Sports equipment.
- Transportation.
- Lunch-related costs.
If you expect the total to be $600 and have six months before the purchases are needed, setting aside $100 per month can prevent the expense from landing entirely on one paycheck.
Before shopping, check what your children already have. Last year’s unused notebooks, clothing that still fits and working electronics do not need replacing simply because retailers have launched back-to-school promotions.
19. Budget for Birthdays Without Overspending
Children’s birthdays can become expensive quickly because spending often extends beyond the gift.
A birthday budget might include:
| Expense | Planned amount |
|---|---|
| Gift | $75 |
| Cake/food | $50 |
| Party/activity | $100 |
| Decorations | $25 |
| Miscellaneous | $25 |
| Total | $275 |
If you have three children and expect to spend $275 per birthday, that is $825 per year before gifts for classmates and relatives.
Adding birthday spending to a sinking fund spreads the cost across the year.
Children can enjoy birthdays without every celebration becoming larger than the previous one. Decide what your household can afford before looking at party packages and social-media inspiration.
20. Prepare for Medical and Dental Costs
Insurance does not always eliminate out-of-pocket healthcare expenses.
Families may face deductibles, copays, prescriptions, dental treatment, glasses, therapy or other costs.
Review what your family spent during the previous year and identify recurring expenses that can be budgeted in advance.
If your country or employer provides tax-advantaged healthcare accounts or similar benefits, understand the rules before using them.
A known dental treatment scheduled six months from now belongs in the budget. A genuinely unexpected medical bill may require emergency savings.
Again, separating predictable and unpredictable expenses makes the entire system easier to manage.
21. Use a Weekly Spending Limit When Monthly Budgets Feel Too Abstract
A $1,000 flexible-spending budget can feel large at the beginning of the month and suddenly disappear by week three.
Breaking selected categories into weekly limits can make spending easier to control.
Suppose your monthly grocery and household-goods target is $800. You might begin with a weekly planning figure around $185–$200 while keeping a small buffer for the difference between weeks and months.
The same approach can work for:
- Groceries.
- Restaurants.
- Entertainment.
- Children’s extras.
- Personal spending.
Fixed bills such as rent do not need weekly limits.
Weekly planning is simply a way to receive faster feedback. Instead of discovering at the end of the month that spending exceeded the target, you can adjust after the first week.
22. Try a Family Budget Meeting
If more than one adult makes financial decisions in the household, one person should not have to carry the entire mental load.
A short budget meeting once or twice a month can keep both adults informed.
Discuss upcoming bills, unusual expenses, savings goals and purchases that need planning.
Keep the meeting focused on decisions rather than blame.
Questions can include:
- What unusual expense is coming next month?
- Did any category run significantly over budget?
- Is a subscription no longer useful?
- Do we need to adjust a sinking fund?
- Are we still saving toward our current goal?
- Is a large purchase coming soon?
Children can also be included in age-appropriate money conversations without exposing them to unnecessary financial anxiety.
23. What If Your Expenses Are Higher Than Your Income?
Sometimes budgeting reveals a problem that better organization cannot solve: the household consistently spends more on necessary expenses than it earns.
Start by separating the deficit into two possibilities.
First, determine whether significant flexible spending can realistically be reduced. Second, calculate whether the budget would still be negative even after those cuts.
If essentials alone exceed income, the problem may require larger changes such as increasing income, changing housing or transportation costs, restructuring debt, accessing benefits or changing childcare arrangements.
Do not spend hours trying to save $5 on groceries if the budget has a $1,000 monthly structural deficit.
A budget cannot create money that does not exist. Sometimes the numbers are telling you that the solution must be bigger than cutting small purchases.
24. Budgeting for Single Moms
Budgeting for single moms can involve additional pressure because one adult may be responsible for both earning income and managing most household decisions.
Start by distinguishing reliable income from money that may not arrive consistently.
If child support is irregular, building every essential expense around receiving it on time can create problems. Where possible, use conservative assumptions and decide in advance how additional money will be allocated when it arrives.
Emergency savings can also be especially valuable in a one-income household because there is no second salary automatically available after a job disruption.
At the same time, do not assume every financial problem can be solved through extreme frugality.
Check whether your household qualifies for government programs, childcare support, tax benefits, healthcare assistance, school programs or other legitimate resources available where you live.
Using a program for which you qualify is part of financial planning, not a budgeting failure.
25. Budgeting for Stay-at-Home Moms
A stay-at-home mom may not receive a paycheck, but household budgeting still needs to account for both adults’ needs and long-term security.
The family should understand the value and financial implications of unpaid caregiving.
Review retirement arrangements, insurance, access to accounts and emergency plans. Both partners should know how household finances work and how to access essential financial information.
Personal spending should also be discussed explicitly.
A stay-at-home parent should not have to request permission for every minor personal expense simply because income arrives through the other partner’s paycheck.
A healthy household budget treats money as a family resource while maintaining transparency and appropriate financial independence for both adults.
26. Should Moms Use the 50/30/20 Budget?
The 50/30/20 approach divides after-tax income broadly among needs, wants and savings/debt goals. It can provide a useful starting framework, but it should not become a rule that makes you feel as though your family is failing.
Childcare alone can dramatically change the percentages for a family with young children. Housing costs also vary enormously by location.
If necessities consume 70% of income, writing 50% in a budget will not change reality.
Use percentage-based systems as diagnostic tools rather than laws.
If your percentages are far from the guideline, investigate why. The explanation may reveal an area worth changing – or simply show that your family is in an expensive stage of life.
27. Zero-Based Budgeting for Moms
Zero-based budgeting gives every dollar of expected income a purpose.
If household take-home income is $4,500, you assign the entire $4,500 among bills, spending, debt and savings until the unassigned amount reaches zero.
That does not mean spending the entire paycheck.
Money assigned to emergency savings, retirement or a sinking fund is still part of the budget.
Zero-based budgeting can work particularly well for families that want detailed control, but it requires regular updates when expenses or income change.
If that level of detail feels exhausting, use broader categories instead. The best budgeting method is the one you can continue using after the initial motivation disappears.
28. How to Automate a Family Budget
Automation can remove some repetitive work from household finances.
Depending on your banking setup, you may be able to automate:
- Rent or mortgage payments.
- Utilities.
- Insurance.
- Minimum debt payments.
- Transfers to savings.
- Retirement contributions.
- Sinking-fund transfers.
Automation works best when cash flow is predictable enough to support it.
If income varies significantly, automatic withdrawals can create overdrafts when the timing is wrong. In that case, reminders or manual payments after each payday may provide more control.
Keep a list of every automatic charge and its expected date.
Automation should reduce financial stress, not make you lose track of where the money goes.
29. 10 Budgeting Mistakes Moms Can Avoid
Family budgets often fail because the plan does not reflect how family life actually works.
Watch for these common mistakes:
- Budgeting from ideal numbers. Start with actual spending before setting new targets.
- Forgetting irregular expenses. Birthdays and school supplies should not surprise the budget every year.
- Keeping no miscellaneous category. Real life rarely fits perfectly into predefined categories.
- Saving nothing for emergencies. Even a small cushion can help with unexpected bills.
- Making the budget too restrictive. A plan that nobody can follow is not useful.
- Ignoring small recurring charges. Several subscriptions can become meaningful annual spending.
- Budgeting every month identically. Summer, holidays and school seasons can require different plans.
- Putting every extra dollar toward the kids. Parents’ emergency and long-term financial security also matter.
- Leaving one partner uninformed. Both adults should understand the household finances where applicable.
- Giving up after one expensive month. A budget is a tool to adjust, not a test you pass or fail.
A budget should become more realistic over time. If the same category exceeds its target every month, consider whether the target – rather than your discipline – is the problem.
Monthly Budget Template for Moms
Use this template as a starting point and replace every number with your household’s actual income and expenses.
| Budget category | Planned | Actual | Difference |
|---|---|---|---|
| Income | $_____ | $_____ | $_____ |
| Housing | $_____ | $_____ | $_____ |
| Utilities | $_____ | $_____ | $_____ |
| Groceries | $_____ | $_____ | $_____ |
| Childcare | $_____ | $_____ | $_____ |
| Transportation | $_____ | $_____ | $_____ |
| Insurance | $_____ | $_____ | $_____ |
| Healthcare | $_____ | $_____ | $_____ |
| School/kids | $_____ | $_____ | $_____ |
| Debt payments | $_____ | $_____ | $_____ |
| Emergency savings | $_____ | $_____ | $_____ |
| Retirement | $_____ | $_____ | $_____ |
| Sinking funds | $_____ | $_____ | $_____ |
| Entertainment | $_____ | $_____ | $_____ |
| Personal spending | $_____ | $_____ | $_____ |
| Subscriptions | $_____ | $_____ | $_____ |
| Miscellaneous | $_____ | $_____ | $_____ |
| Total | $_____ | $_____ | $_____ |
Complete the “planned” column at the beginning of the month and the “actual” column after transactions occur.
The difference is valuable information. It shows where the next month’s budget needs adjusting.
A Simple Payday Budget for Moms
Monthly budgeting can be difficult when bills and paychecks arrive at different times.
A payday budget solves this by assigning expenses to each paycheck.
Suppose you receive two $2,000 paychecks each month.
| First paycheck | Amount | Second paycheck | Amount |
|---|---|---|---|
| Rent | $1,000 | Rent reserve | $500 |
| Groceries | $300 | Groceries | $300 |
| Utilities | $250 | Childcare | $500 |
| Childcare | $300 | Transportation | $200 |
| Savings | $100 | Debt payment | $200 |
| Transportation | $150 | Sinking funds | $150 |
| Personal/misc. | $100 | Personal/misc. | $150 |
| Total | $2,200* | Total | $2,000 |
*This example deliberately shows a problem: the first paycheck has $2,200 assigned despite only $2,000 arriving.
That is exactly why a payday budget can be useful. It exposes timing problems that a monthly total can hide.
You would need to shift at least $200 of expenses, use money intentionally reserved from the previous paycheck or change due dates where possible.
How Often Should You Update Your Family Budget?
Reviewing the budget once a month is enough for many households.
During periods of major change – parental leave, job loss, a move, new childcare arrangements or rapidly changing income – weekly reviews may be more useful.
You do not need to rebuild the entire budget each time.
Compare planned and actual spending, identify upcoming unusual expenses and change only the categories that need adjustment.
The budget should evolve as children grow.
Diapers may disappear while school activities appear. Daycare may end while sports and technology expenses increase. A budget designed for a toddler will not remain appropriate when that child becomes a teenager.
How to Make Budgeting for Moms Less Stressful
A budget works best when it reduces uncertainty rather than creating another source of pressure.
You do not need 40 categories, a complicated app or perfect spending behavior.
Know what comes in. Know what must go out. Prepare for expenses you can predict. Keep something aside for those you cannot.
Then use the remaining money intentionally.
If your first family budget reveals that you have less flexibility than expected, that information is useful. You now know which problem needs attention.
If it reveals extra money, give that money a purpose before it quietly disappears.
The goal of budgeting for moms is not to spend as little as possible. It is to make sure your family’s money supports the things that matter most without every unexpected expense becoming a financial crisis.
FAQ
There is no single best method. Zero-based budgeting can provide detailed control, while category or paycheck budgeting may be easier for other households. The best approach is one that reflects your real income and expenses and is simple enough to maintain.
Start by calculating household take-home income and reviewing several months of actual spending. Separate essential expenses, flexible spending, debt and savings, then create realistic monthly targets.
Common categories include housing, utilities, groceries, childcare, transportation, insurance, healthcare, school expenses, debt payments, savings, sinking funds, personal spending and entertainment.
Separate regular costs from irregular expenses. Include monthly childcare and food in the normal budget, while using sinking funds for clothing, birthdays, school supplies, sports and other predictable costs that occur less frequently.
Build the plan around reliable income, prioritize essential expenses and create an emergency cushion when possible. If income is insufficient for necessities, investigate legitimate benefits, childcare assistance, debt support and opportunities to increase income rather than relying only on small spending cuts.
There is no universal amount. Choose a contribution that fits your income, essential expenses and financial goals. Even small regular contributions can help establish an emergency fund and savings habit.
The appropriate amount depends on household expenses, job stability, number of earners and other factors. A small starter fund can help with minor emergencies, while larger reserves can provide protection during longer income disruptions.
A sinking fund is money saved gradually for a known future expense such as Christmas, children's clothing, school supplies or car maintenance. It is different from an emergency fund because the expense is expected.
Start by tracking current grocery spending. Plan meals, shop from a list, check existing food before buying more, compare unit prices and reduce food waste. Set a realistic target rather than attempting an unsustainable cut.
It can be a useful framework, but family costs such as childcare and housing can make the percentages unrealistic. Treat it as a guideline rather than a requirement.
Use a conservative income estimate for essential expenses and decide in advance how additional income will be allocated during stronger months. Building cash reserves can also help smooth variable income.
The answer depends on individual circumstances, but parents should not automatically abandon retirement saving for children's education. Education may have multiple funding options, while retirement generally cannot be financed in the same way.
Keep the system simple, use realistic spending targets, prepare for irregular expenses and review actual spending regularly. If a category repeatedly exceeds its target, adjust either the spending behavior or the target rather than abandoning the entire budget. how to start an online business with no money
Dmytro Mykhailenko is a financial expert and a prolific author specializing in articles about money and economics. With a deep understanding of financial matters, he provides readers with valuable insights into financial planning, investing, and economic trends. His informative and practical articles help readers navigate complex financial issues and make well-informed decisions.